The Tax Perks of Being a Solopreneur: How Working for Yourself Can Work in Your Favor
Being your own boss has its perks. You set your schedule, choose your clients, and make the big decisions. But one of the most overlooked advantages of being a solopreneur? The potential tax savings.
While traditional employees typically have limited opportunities to deduct work-related expenses, self-employed business owners have access to a range of deductions, retirement savings options, and tax strategies that can help them keep more of what they earn.
Of course, those benefits don't happen automatically. Understanding the tax advantages available to you, and planning ahead to maximize them, can make a meaningful difference in your bottom line.
Let's break down some of the biggest tax perks of flying solo.
1. Your Business Expenses Can Lower Your Taxable Income
One of the biggest advantages of being self-employed is the ability to deduct qualifying business expenses. Generally, the IRS allows business owners to deduct expenses that are both ordinary and necessary for operating their businesses.
Depending on your business, those deductions might include:
Technology and software: Laptops, subscriptions, accounting software, and other business tools.
Marketing and advertising: Website hosting, branding, digital advertising, and promotional materials.
Professional services: Fees paid to accountants, bookkeepers, attorneys, and consultants.
Business travel: Qualifying transportation, lodging, and certain meal expenses associated with business activities.
Education and development: Training, conferences, and courses that maintain or improve skills used in your current business.
Office supplies: Everything from printer paper to business equipment.
The key is keeping accurate records and ensuring expenses have a legitimate business purpose.
Tax Planning Tip: Don't wait until tax season to organize your expenses. Tracking them throughout the year helps you identify deductions, maintain cleaner books, and make better financial decisions.2. Your Home Office Could Be a Tax Deduction
Working from your kitchen table might be convenient, but having a dedicated home office could offer an additional tax advantage. If you use part of your home regularly and exclusively for qualifying business purposes, you may be eligible for the home office deduction.
There are generally two ways to calculate it:
Simplified Method: Deduct $5 per square foot of qualifying home office space, up to 300 square feet, for a maximum deduction of $1,500.
Actual Expense Method: Deduct the qualifying business portion of eligible household expenses, potentially including utilities, insurance, rent, mortgage interest, and certain repairs.
The best method depends on your individual circumstances, including the size of your workspace and your actual household expenses.
Tax Planning Tip: A dedicated workspace can potentially save you money at tax time, but the IRS has specific requirements. Make sure your space qualifies before claiming the deduction.
3. You Can Build Retirement Savings While Reducing Taxes
When you're self-employed, there's no employer automatically enrolling you in a retirement plan. But that doesn't mean you're missing out on valuable retirement benefits. Solopreneurs have access to retirement savings options that can offer significant tax advantages.
Two popular choices include:
Solo 401(k)
Designed for business owners with no employees other than a spouse, a Solo 401(k) may allow you to contribute in both an employee and employer capacity, subject to annual limits and other rules.
SEP IRA
A Simplified Employee Pension (SEP) IRA allows eligible self-employed individuals to make tax-deductible retirement contributions based on qualifying compensation or self-employment earnings.
Both options can help you prepare for the future while potentially reducing your current taxable income through traditional, tax-deductible contributions.
Tax Planning Tip: Retirement contributions aren't just about saving for later. Choosing the right plan and contribution strategy can be an important part of your annual tax planning.4. You May Qualify for the Qualified Business Income Deduction
Here's a tax benefit that many solopreneurs overlook: the Qualified Business Income (QBI) deduction.
Eligible self-employed individuals and owners of pass-through businesses may qualify to deduct up to 20% of their qualified business income, subject to applicable limitations.
For example, a solopreneur with $100,000 in qualified business income could potentially qualify for a deduction of up to $20,000, depending on their taxable income, business type, and other factors.
That's a potentially meaningful reduction in taxable income without having to spend additional money on business expenses.
The deduction generally applies to qualifying sole proprietorships, partnerships, S corporations, and certain other pass-through businesses.
Tax Planning Tip: The QBI deduction has specific eligibility requirements and income-based limitations. Working with a tax professional can help you determine how much of the deduction you can actually claim.5. Health Insurance Premiums May Be Deductible
One of the biggest concerns for people leaving traditional employment is the cost of health insurance.
Fortunately, eligible self-employed individuals may be able to deduct qualifying health insurance premiums for themselves, their spouses, and eligible dependents. This deduction can potentially include medical, dental, and qualifying long-term care insurance premiums.
Unlike many itemized medical expense deductions, the self-employed health insurance deduction is generally an adjustment to income, meaning eligible taxpayers may benefit even if they don't itemize.
However, eligibility restrictions apply, including rules related to employer-sponsored coverage and business income.
Tax Planning Tip: If you're paying for your own health insurance, make sure those premiums are part of your annual tax planning conversation.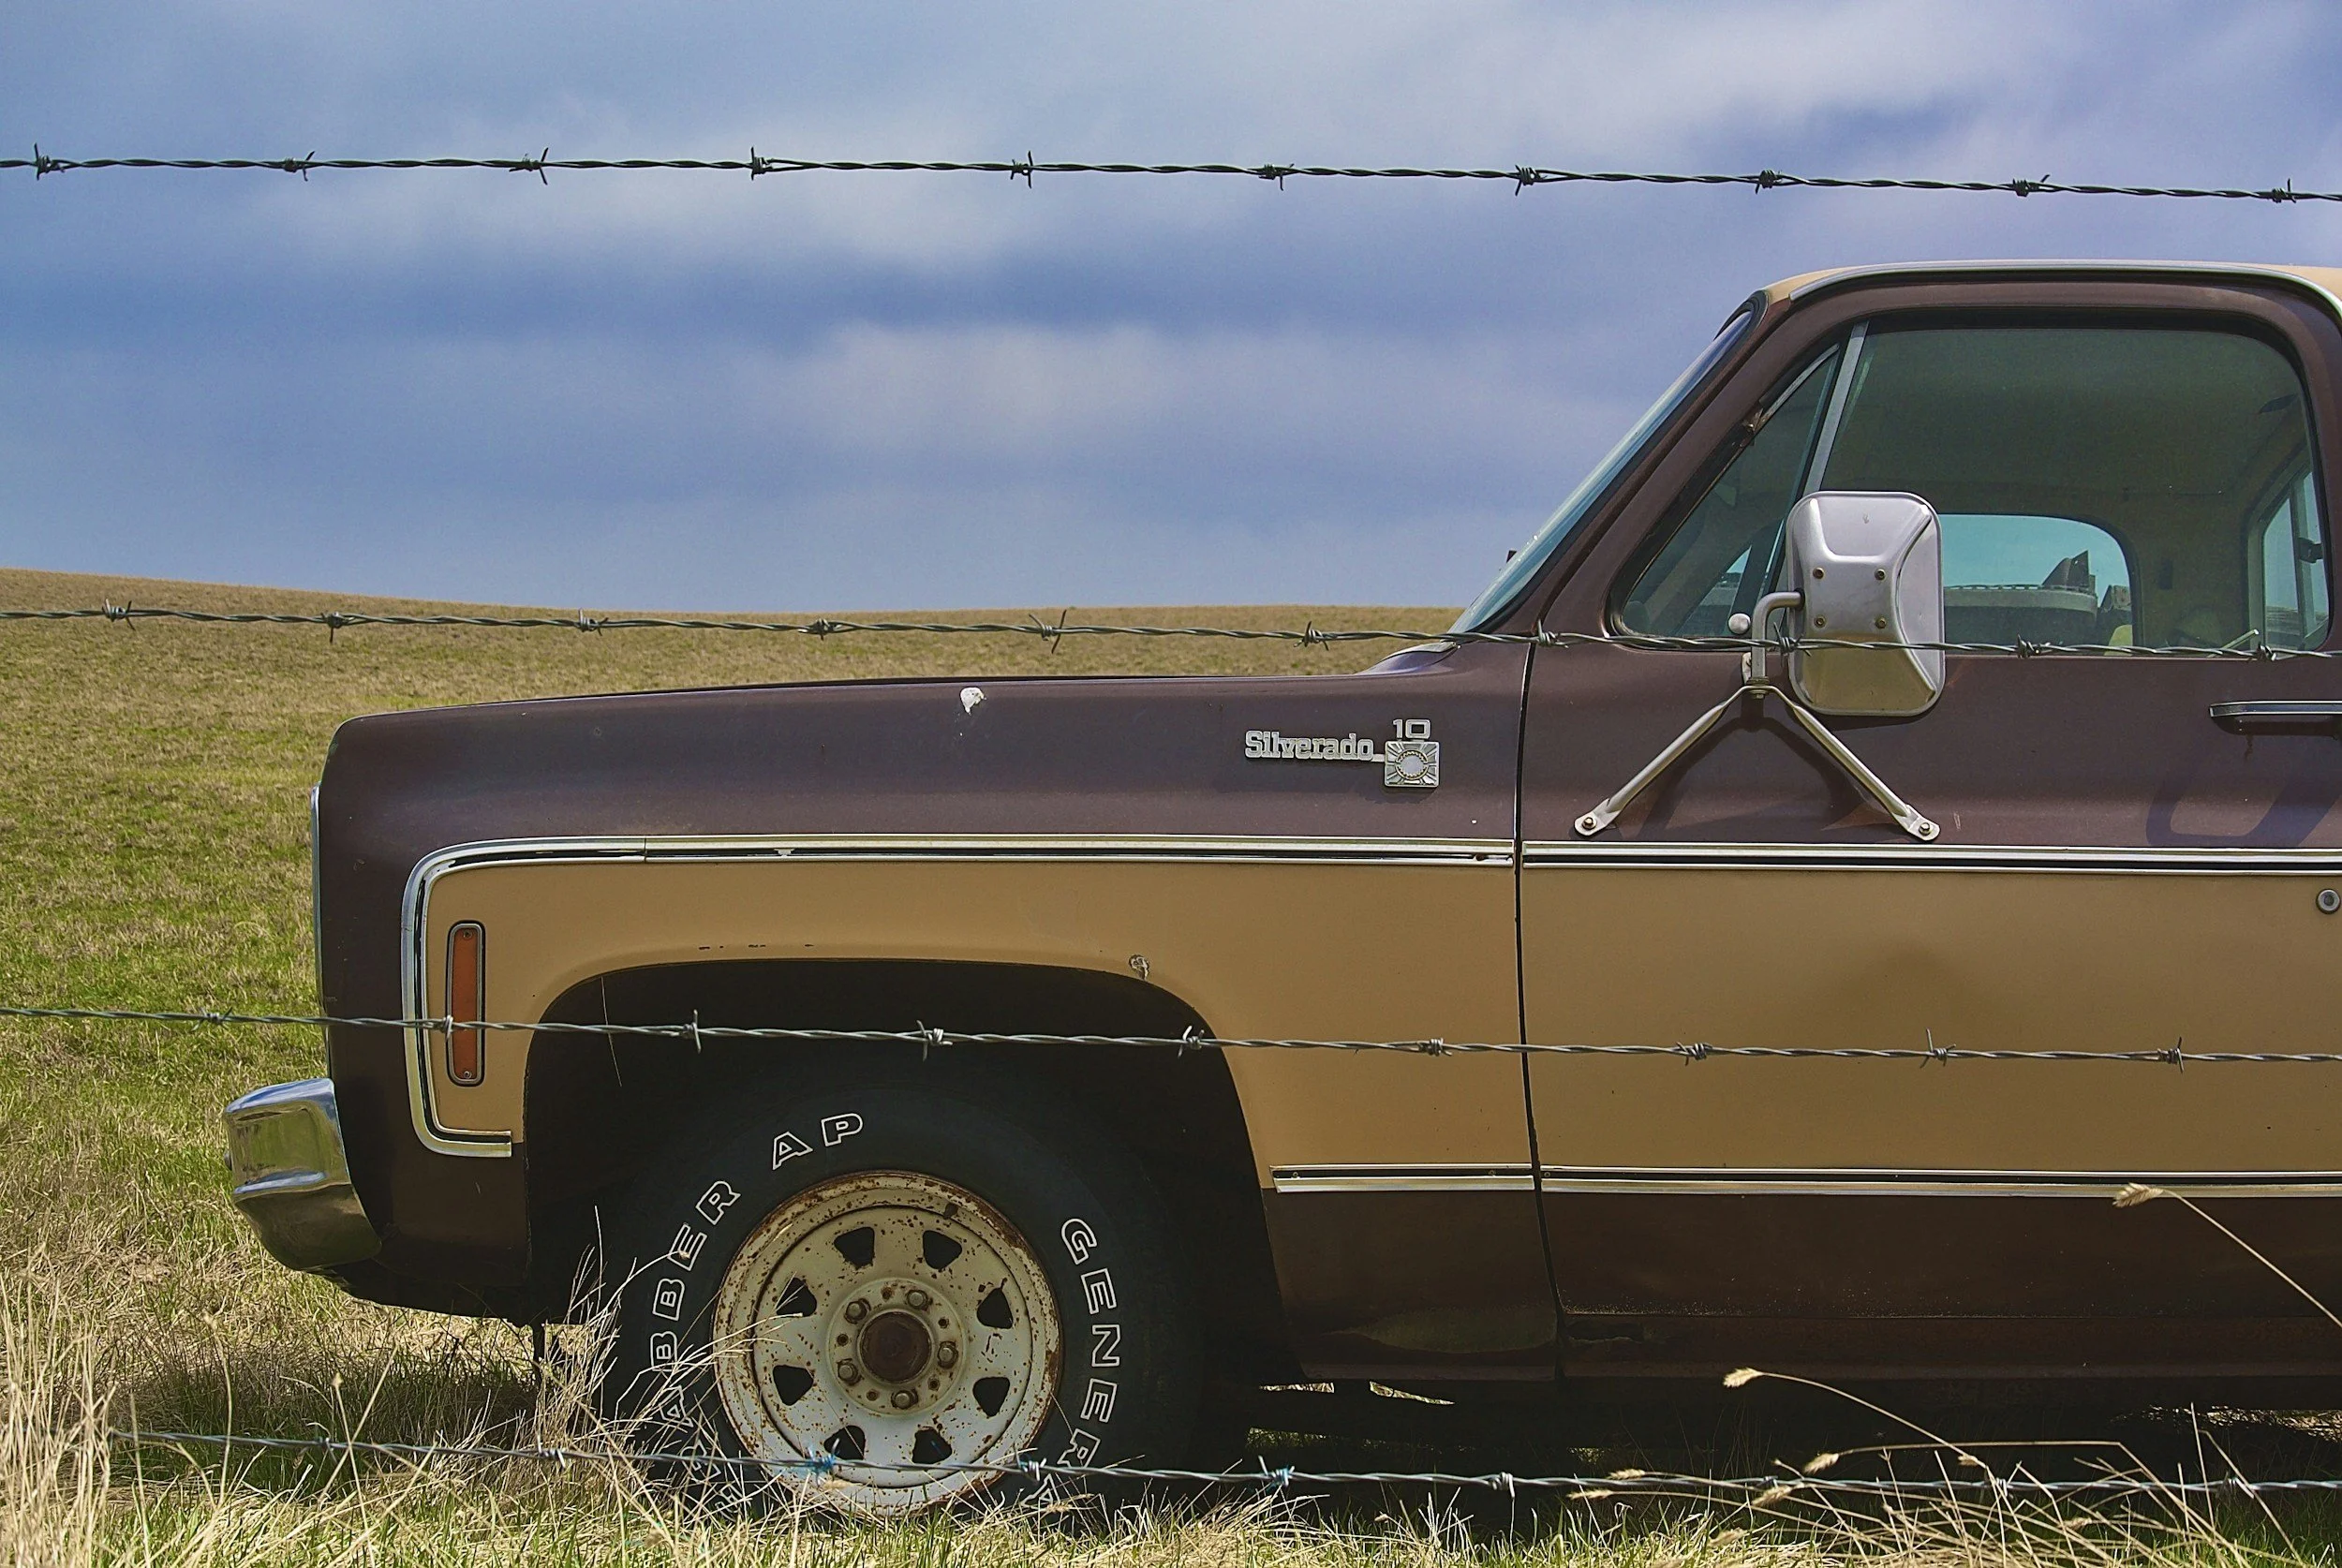
The Ranch Truck is a Work Vehicle, Expense Those Miles
Whether you're traveling to meet clients or checking the fence on your hobby beef cattle operation, eligible business mileage can add up over the course of a year.
6. Your Vehicle and Mileage Could Generate Tax Savings
If you use your personal vehicle for business, you may be able to deduct qualifying vehicle expenses. Whether you're traveling to meet clients, visiting job sites, or driving between business locations, eligible business mileage can add up over the course of a year.
The IRS generally allows two approaches:
Standard Mileage Method: Deduct qualifying business miles using the applicable IRS mileage rate.
Actual Expense Method: Deduct the eligible business-use percentage of vehicle expenses such as fuel, maintenance, insurance, and depreciation.
Not every trip counts. Ordinary commuting between your home and a regular workplace is generally not deductible.
Tax Planning Tip: Keep a mileage log throughout the year. Trying to reconstruct business travel months later can lead to missed deductions and unnecessary headaches.7. You Have More Control Over Tax Planning
Perhaps the most valuable financial advantage of being a solopreneur is the ability to make strategic decisions about how you operate your business.
As a self-employed professional, you may have opportunities to plan around:
Business investments: Timing necessary equipment purchases and other deductible expenses.
Retirement contributions: Adjusting eligible contributions based on profitability and financial goals.
Entity structure: Evaluating whether operating as a sole proprietor, LLC, or electing S corporation taxation makes sense for your business.
Estimated tax payments: Planning quarterly payments to manage cash flow and avoid potential penalties.
Income and expense timing: Understanding how legitimate timing decisions may affect your taxable income.
For some profitable solopreneurs, an S corporation election may offer potential self-employment tax savings. However, those savings must be weighed against reasonable compensation requirements, payroll obligations, and additional administrative costs.
The right strategy depends on your business, income, and long-term goals.
Tax Planning Tip: The best tax strategy isn't necessarily the one that creates the largest deduction. It's the one that supports your overall financial health while keeping you compliant.Don't Forget: Being Your Own Boss Comes With Tax Responsibilities
While self-employment offers valuable tax advantages, it also comes with responsibilities that traditional employees don't always have to manage.
Solopreneurs generally need to account for self-employment taxes, federal and potentially state income taxes, estimated tax payments, and accurate financial recordkeeping. Without proper planning, even a profitable business can find itself facing an unexpected tax bill.
That's why proactive tax planning is so important.Make Your Independence Pay Off
Being a solopreneur means taking control of your career, your time, and your financial future. It also means having access to tax-saving opportunities that can help you build a more financially efficient business.
But here's the catch: You can't maximize tax benefits you don't know exist.
From business expense deductions and retirement contributions to strategic entity planning, the decisions you make throughout the year can have a meaningful impact on what you owe at tax time. The earlier you start planning, the more opportunities you may have to make those decisions work in your favor.
Ready to Make the Most of Your Solopreneur Tax Benefits?
You don't have to navigate the tax side of entrepreneurship alone.
Working with an experienced tax and accounting professional can help you identify available deductions, stay ahead of tax obligations, and develop a proactive strategy that supports your business goals.
Because being your own boss should come with financial freedom, not tax-season surprises. Reach out to see how we can help you maximize your soloprenuer benefits:
Disclaimer: This article provides general information about U.S. federal tax rules and is not individualized tax advice. Eligibility, deduction limits, and tax treatment depend on individual circumstances and applicable tax-year rules. Consult a qualified tax professional before making tax decisions.
